May 2026.
CEVES Newsletter
Dear friends, associates, and partners,
We share with you the bulletin for the first quarter of 2026, in which we examine an economy that, at first glance, shows a somewhat better result than during last year’s slowdown, yet without signs of a broad and sustainable recovery. Behind the preliminary growth rate of 3.0%, the exhaustion of a development model long reliant on public spending, large projects, and a narrow set of export sectors is becoming ever more apparent, while the domestic private sector still lacks a sufficiently strong foundation for a new investment and productivity impulse.
In the CEVES Observatory, we demonstrate that growth in the first quarter does not rest on a broad economic recovery, but on limited sources: growth in wages (especially in the public sector) and pensions, EXPO, motor vehicle exports, mining, and inventories. Of particular concern is the fact that recovery has yet to materialise in investment, manufacturing, and domestic SMEs — precisely those segments of the economy that would need to compensate for the weakening of the growth drivers that have prevailed until now.
However, current economic policy continues to undermine competitiveness.
In the CEVES Position, we argue that the latest changes to the rules governing the adoption of regulations are not a technical acceleration of EU alignment, but rather a circumvention of the public — and a serious blow to the expertise and professionalism of the public administration. This weakens precisely what should serve as the foundation of Serbia’s European path: accountable decision-making, justified public policies, and institutions that operate in the public interest.
CEVES Observatory
The start of 2026 appears to bring a somewhat higher growth rate, but weaker prospects for future growth. Following the slowdown in GDP growth from 3.9% in 2024 to 2.0% in 2025, the partial recovery to 2.2% in Q4 did not signal a return to stronger private-sector growth. If the flash estimate of 3.0% for Q1 2026 is not overstated, it reflects the same pattern. Growth continues to rest on real wage growth and current public expenditure, EXPO and residential construction, and a handful of large export anchors — primarily linked to Stellantis, Zijin, and rubber industry FDI. The rest of the economy is stagnating or decelerating.
Public expenditure and real wages continued to drive consumption, housing demand, and infrastructure projects. Year-on-year fiscal loosening in Q1 2026 (measured through the primary deficit excluding Rafale payments and capital expenditure) amounted to approximately 1.2% of quarterly GDP, or around €250 million. This is the result of a 14.3% rise in current expenditure, with growth in wages, pensions, goods, and services ranging from 10–16%. Real wages rose 8.5% year-on-year in January and February, partly due to public-sector wages and a roughly 10% real increase in the minimum wage, and partly due persistently unaddressed labour-market mismatches. This contributed to the largest year-on-year increase in real retail trade turnover in seven quarters (8%). Housing demand also remained strong, with residential mortgage lending to households growing by more than 60% year-on-year for the sixth consecutive quarter. Together with state capital expenditures related to EXPO and investments by EPS and EDS, these factors largely explain the 8.9% investment growth recorded in Q4 2025. A similar trend is continuing into Q1 2026.
Private investment most clearly demonstrates the absence of recovery. New investment loans to enterprises, after growing by 46.2% in 2024, slowed to 13.0% in 2025, came to a near standstill in Q4 2025, and fell by as much as 18.9% year-on-year in Q1 2026. For SMEs, the decline was 23.7%. FDI followed the same trajectory: inflows fell 34% in 2025, and were nearly 30% lower year-on-year in January and February 2026. Furthermore, the apparent recovery of investment from the EU and in the manufacturing sector is largely illusory, as it consists predominantly of Chinese companies (Linglong and Zijin) domiciled in the Netherlands. Announcements of new FDI for 2026 are likewise largely confined to smaller Chinese investments in automotive and EV-related activities, while foreign suppliers in labour-intensive sectors continue to announce closures and reductions in activity.
Production and exports reveal how narrow Serbia’s competitiveness base has become. Continuing the trend from Q4 2025, overall industrial production fell by 0.8% in Q1 2026, with manufacturing declining by 0.4%. Excluding electricity, goods exports grew by 9.1%, but almost all of the increase came from Stellantis, rubber-sector FDI, Zijin and the rest of basic metals. Outside these anchors, the rest of industry is at best stagnant or oscillating, while textiles, clothing, and furniture continue to weaken. Services exports played a stabilising role in 2025 — primarily through business services — while ICT gradually decelerated. Nevertheless, services exports fell by 1.7% in January and February, with business services and ICT now also stagnating.
Labour market dynamics illustrate how competitiveness pressures are translating into employment. Wages have continued to grow faster than productivity, and the deceleration in unit labour cost growth in 2025 came primarily through headcount adjustment rather than productivity gains. In Q1 2026, registered employment fell modestly overall but declined by 3.3% in manufacturing. Reported employer demand for labour fell by 22% in March, while the number of unemployment benefit recipients rose by 13%. Having already lost its cost-competitiveness advantage relative to all Central and Eastern European countries, Serbia can sustain (wage) growth only through productivity growth. Yet the policy focus remains largely elsewhere – on policies that continue to erode rather than strengthen Serbia’s competitiveness.
CEVES Stance
New Decrees — A New Circumvention of EU Acquis Alignment
CEVES calls on all those concerned with good governance in Serbia to oppose the recently adopted amendments to the decrees governing the process of adopting new regulations and public policies (hereinafter “regulations”). Through these amendments, the Government has exempted itself from the obligation to subject new regulations to public consultation and to submit them for assessment to the Republic Secretariat for Public Policies (RSJP).
This exemption applies “only” to cases where a regulation concerns “alignment with EU law”
— which in practice can encompass virtually any regulatory change.
Consider the case of the “Mrdić laws” on the prosecution service. Those measures were so undemocratic and un-European that the European Commission prompted the Venice Commission to issue an expedited opinion on them. That opinion is now being discussed through the wrong procedure, and although it is unusually detailed and directive in nature, it is difficult to believe that all substantive matters will be restored to their previous state. The hardest to restore will be the most important: ensuring that all professional and dedicated prosecutors who worked on sensitive cases within the Special
„of the ”Mrdić laws" on the prosecution. Those measures were so undemocratic and non-European that the EC initiated the Venice Commission to provide an opinion on them urgently. That opinion is now being discussed through the wrong procedure, and although the opinion is unusually detailed and directive – it is difficult to believe that all essential matters will be restored to their previous state. The most difficult will be the most important – that all professional and diligent prosecutors who worked on sensitive cases in TOK return to them.
In other words, the “European” opinion may formally patch things up, but by then the damage will already have been done. If these decrees remain in force, neither civil society nor the RSJP will be able to flag problematic regulations in time. By “problematic” we mean not only measures that are undemocratic, but also the range of possible “well-intentioned” errors and inconsistencies that the RSJP and civil society currently identify before they cause harm.
The RSJP is not just any institution. It is arguably the most important — and certainly the most unique — achievement of nearly a decade and a half of effort, and substantial EU funding, invested in improving the functioning of Serbia’s administration, and in particular in building the “centre of government” without which serious state governance is simply not possible. The EU itself has on countless occasions underscored “the importance of the strong quality control role of the Republic Secretariat for Public Policies and other centre-of-
government institutions.” I therefore hope it will promptly recognise that with this manoeuvre, the regime is significantly raising the temperature of the pot in which it has been boiling us, like frogs, for a decade. Should the decrees remain in force, the first reform achievement to be lost will be the RSJP itself — the remaining professionals will begin to leave. That will be the first casualty, but certainly not the last.
JFor more on this topic,, and for an excellent analysis by attorney Đorđe Vukotić, please click here.
— Kori Udovički
Launch of CEVES's first economic governance report and panel discussion
On April 16, 2026, CEVES presented the report „Governance for Competitiveness: An Initial Assessment of Economic Governance,“ prepared with the support of the Delegation of the European Union to Serbia. This is CEVES's first report of its kind, which examines economic governance in Serbia through the prism of competitiveness, i.e., through the ability of the economy to achieve broad-based productivity growth and withstand competitive pressures in the process of approximating the European Union. The report was first published on the website at the very end of 2025, and presented in April 2026 as an initial assessment within a broader research cycle that CEVES will continue through annual reports. Work on the next edition has already begun with the renewed support of the Delegation of the European Union to Serbia.
The report analyses the first sub-criterion of a functioning market economy — economic governance — and its effects on competitiveness, productivity, and the sustainability of Serbia’s growth model. Methodologically, the analysis combines a comparative tracking of Serbia’s convergence towards the EU, a sectoral analysis of productivity and tradable activities, an examination of macroeconomic and real indicators, and a fiscal analysis of public expenditure and business support instruments. You can find the detailed methodology hereThe main finding is that Serbia has achieved macroeconomic stabilisation and gradual approximation to the EU over the past decade, but that this progress is constrained by slow productivity growth — particularly in the sectors underpinning export competitiveness and long-term economic resilience. The report highlights that the prevailing growth model has relied excessively on public investment, subsidised FDI, and cheaper labour, while the domestic private sector, technological upgrading, and small and medium-sized enterprises have remained insufficiently supported. This combination of policies creates the risk of a “manufactured Dutch disease” — that is, rising costs and prices without commensurately strong real productivity growth, thereby gradually eroding the competitive advantage Serbia had built, as a result of errors in economic policy management.
The report's recommendations are focused on measures that can directly improve transparency, support for exports and the SME sector, monitoring of public investments and the quality of economic governance, as well as on preparing a broader institutional shift towards a growth model based on productivity. You can view the report here.
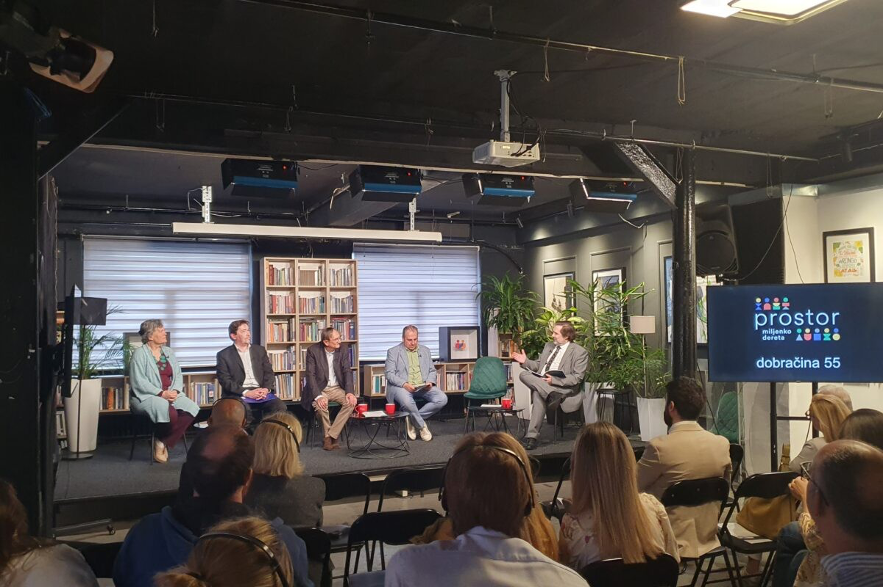
Photo: Forbes Serbia
Following the report launch, a panel discussion was held, moderated by Prof. Dr. Branko Radulović, with the participation of Academician Pavle Petrović, Prof. Dr. Miodrag Jovanović, Dr. Kori Udovički, Prof. Dr. Jasna Atanasijević, and Dr. Andrej Bartosiewicz of the EU Delegation to Serbia. The discussion underscored one of the report’s key messages: without the rule of law — encompassing not only an independent judiciary but also the professional, autonomous, and accountable functioning of executive institutions — Serbia cannot generate the productivity growth and genuine development of the domestic economy needed to escape the impasse of its current growth model.
The key message of the panel was that Serbia must make a developmental shift, from growth based on cheap labor and selective support to an economy based on productivity, domestic entrepreneurship, and equal rules of the game.
As Pavle Petrović pointed out, growth based on „mass employment of cheap labor” and investments with low added value „is not sustainable in the long term.”.
Miodrag Jovanović emphasised that without inclusive institutions there can be no “fundamental equality before the law,” while Kori Udovički stressed that in the pursuit of the rule of law, attention must be directed not only at the judiciary but also at the administration. In the same vein, Jasna Atanasijević noted that reforms require equipping civil servants with the capacity to assess the objective of a regulation and the effects expected from it. Andrej Bartosiewicz argued that transparency in state aid reduces the scope for special arrangements with individual companies. Only such a model can ensure that Serbia’s growth is not merely faster, but fairer, more resilient, and grounded in the creation of genuine domestic value.
Your CEVES Team
Kori Udovički, Pavle Medić, Ivona Janović, Dušan Kovačević, Velibor Tatić, Vojislav Stojanović, and Jana Stanković
Copyright © CEVES, All rights reserveded